The state plans to change the rules for the recovery of tax debts in cases of a transfer of an undertaking. It appears that new rules may emerge in the competition between creditors.
Let us imagine the following situation: a company has become insolvent, its business activities have effectively been transferred to another company, but the old debts have not disappeared.
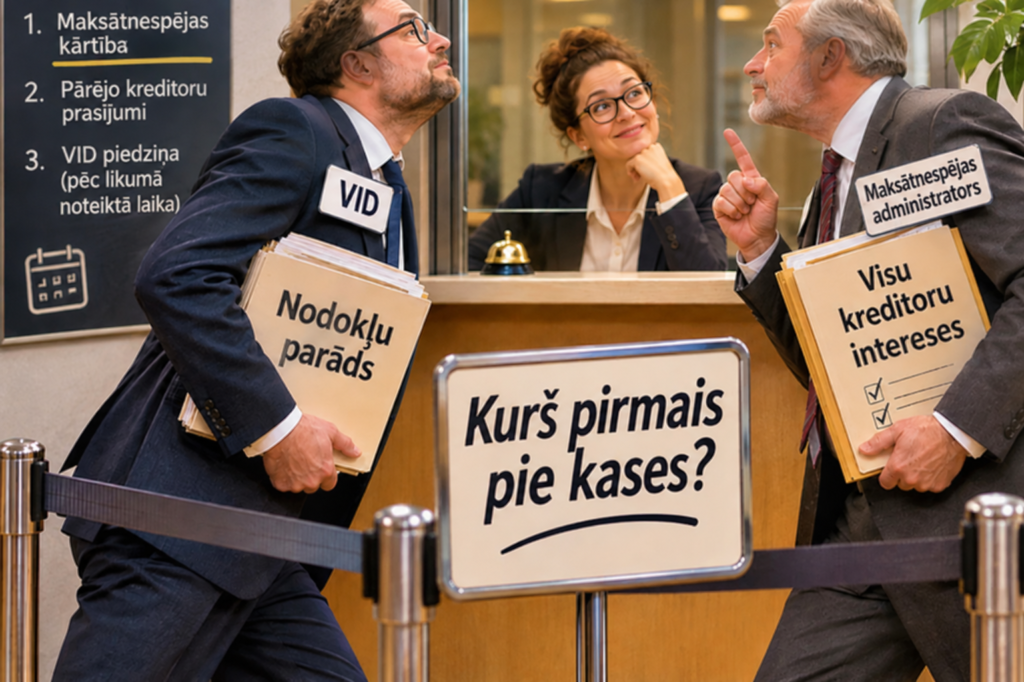
Two interested parties knock on the door of the acquiring company.
State Revenue Service (SRS): “We have unpaid taxes here!”
Insolvency Administrator: “But I have to protect the interests of all creditors!”
And so the question arises: who will get to the money first?
The current regulatory framework allows for a situation in which the SRS, on the basis of Section 20 of the Commercial Law, recovers a tax debt from the acquirer of an undertaking through an uncontested procedure, while the insolvency administrator seeks to recover funds in the interests of all creditors. As a result, the state may receive its claim outside the insolvency proceedings, while the remaining creditors are left hoping that something will still be left.
What changes are being proposed? The draft law No. 26-TA-770, advanced by the Ministry of Justice, provides for supplementing Section 26, Paragraph six of the Law on Taxes and Duties with a new Clause 7. If insolvency proceedings have been declared in respect of the transferor of the undertaking, the SRS would not be able to initiate or continue the uncontested recovery of the relevant tax debt against the acquirer of the undertaking on the basis of Section 20, Paragraph one of the Commercial Law, for as long as the circumstances for suspending recovery specified by law remain in effect. This would give the insolvency administrator the opportunity to act in the interests of all creditors rather than compete with the SRS over who can recover the money first.
Put simply, the SRS will have to wait in line. How long will the SRS have to wait? Not indefinitely! The suspension of recovery would continue until the circumstances specified in the draft law arise, for example, when a plan for the sale of assets or a report on the absence of assets has been prepared in the insolvency proceedings and the administrator has notified that they do not intend to bring a claim against the acquirer of the undertaking, or until the insolvency proceedings of the legal entity are terminated. Thus, the door is not being closed to the SRS. It simply has to wait in the waiting room for a while.
The most interesting part is that the state itself acknowledges the problem! In the explanatory memorandum to the draft law, the Ministry of Justice indicates that a situation in which the SRS, as one of the creditors, recovers a debt outside the insolvency proceedings, thereby reducing the funds available to other creditors, is contrary to the principles of equal treatment of creditors and the prohibition of arbitrariness enshrined in the Insolvency Law. In other words, the state has recognised that, in the race for the debtor’s money, the advantages previously enjoyed by the SRS do not always align with the rules of fair competition between creditors. And this time, it is the state itself that is proposing to change the rules!
However, the SRS is not being given a permanent red card. Recovery would be suspended only for the period specified by law, giving the administrator the opportunity to assess whether to bring a claim against the acquirer of the undertaking.
Does this mean that the acquirer of an undertaking will be able to take over a business and forget about its debts? No! It will not be that simple. Section 20 of the Commercial Law is not going anywhere. If a transfer of an undertaking has taken place, liability for the undertaking’s obligations may still arise.
The amendments provide for a change in the recovery procedure, not the abolition of liability for the undertaking’s obligations. Likewise, the planned amendments do not, in themselves, mean that all previously adopted SRS recovery decisions would be unlawful.
What will this mean for entrepreneurs? If the amendments are adopted, the procedure for recovering tax debts from the acquirer of an undertaking may change in situations where the transferor of the undertaking is insolvent. At the same time, the insolvency administrator would be provided with greater opportunities to protect the interests of the body of creditors as a whole. For entrepreneurs planning to acquire an undertaking or take over its business activities, it will remain important to assess the risks associated with the transfer of an undertaking, including potential liability for the obligations of the previous undertaking.
Our conclusion
The legislator seems to want to make it clear that even the SRS, as a creditor, is not always entitled to be first at the cash register. Moreover, the most interesting aspect is that this time the state itself has acknowledged the problem, pointing to the need to observe the principle of equal treatment of creditors.
Does this mean that a new era will begin in disputes concerning the transfer of undertakings? Possibly.
But one thing is clear: if the amendments are adopted, the SRS will no longer be able to use this particular uncontested recovery mechanism without taking into account the insolvency proceedings of the transferor of the undertaking. The debt does not disappear. The rules simply change as to who may demand its payment and when.
This article has been prepared on the basis of Draft Law No. 26-TA-770, “Amendments to the Law on Taxes and Duties”, and its explanatory memorandum. The draft law has not yet been adopted, and its final wording may change.
Source: Legislation Portal — Draft Law
©INNOVATOR 11.11.2026.